

Panduan Pengelolaan Arus Kas Bisnis
September 29, 2026
Panduan Lengkap Fractional CFO
September 29, 2026
 Have you ever seen a business where sales seem to be booming, but the owner often gets a headache when having to pay daily operational bills? This phenomenon is very common in the business world. In accounting, there is a classic expression that is very relevant to this situation: “Profit is vanity, cash is sanity, but cash flow is king.”
Profit on paper (income statement) may look happy. However, the real cash capital in the bank account is what determines whether your business can survive tomorrow morning or not. Poor cash flow management is the primary cause why many companies—especially those growing rapidly—suddenly go bankrupt mid-way.
Why Can High-Revenue Businesses Run Out of Cash?
Many novice entrepreneurs think that increasing sales is the only cure to overcome financial problems. Unfortunately, growing without direction can actually become a deadly trap known as overtrading.
There are several fundamental reasons why business cash flow can suddenly dry up:
- Bottleneck in Accounts Receivable: You successfully sell products in large quantities, but buyers use a tempo payment system (30 to 90 days). Invoices pile up as assets, but you don’t have cash to buy new raw materials or pay the team’s salary.
- Accumulation of Dead Stock: Too much capital is tied up in the form of finished goods or inventory in the warehouse that has a very slow turnover. Your money stops moving.
- Timing Mismatch: The schedule of operational expense payment obligations (rent, vendor debt, taxes) falls due much faster than the schedule of cash receipts coming in from customers.
Basic Rules for Managing Healthy Cash Flow
Managing cash flow is not just about recording daily income and expenses in a general cash book. It is about controlling the rhythm and movement of fresh funds so they are always available in safe proportions.
1. Create Cash Flow Projections (Cash Flow Forecasting)
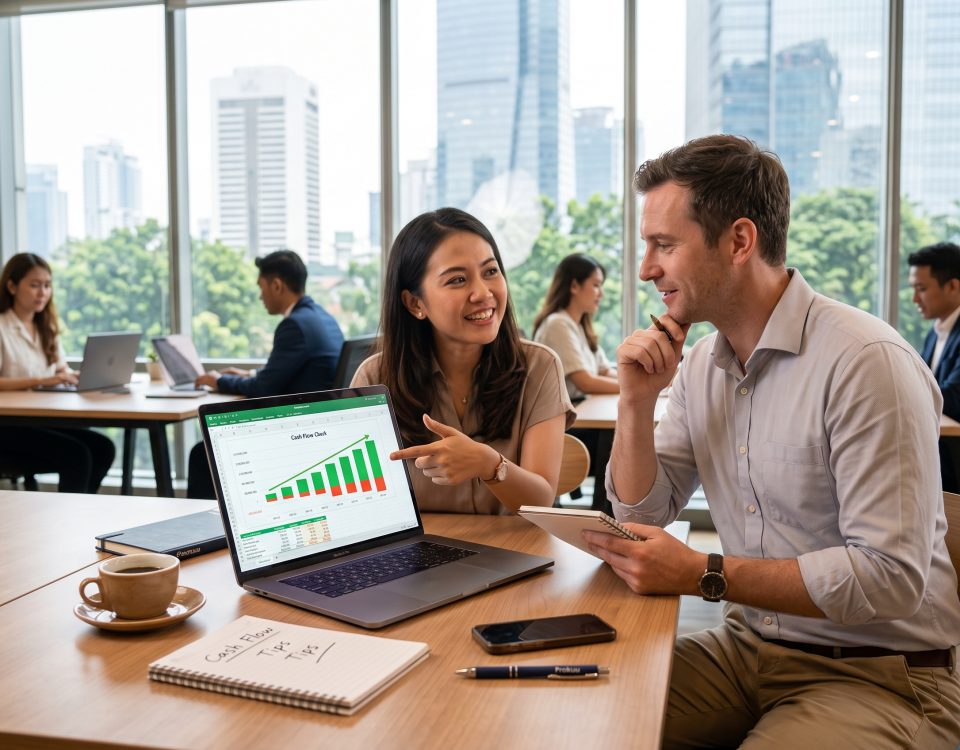
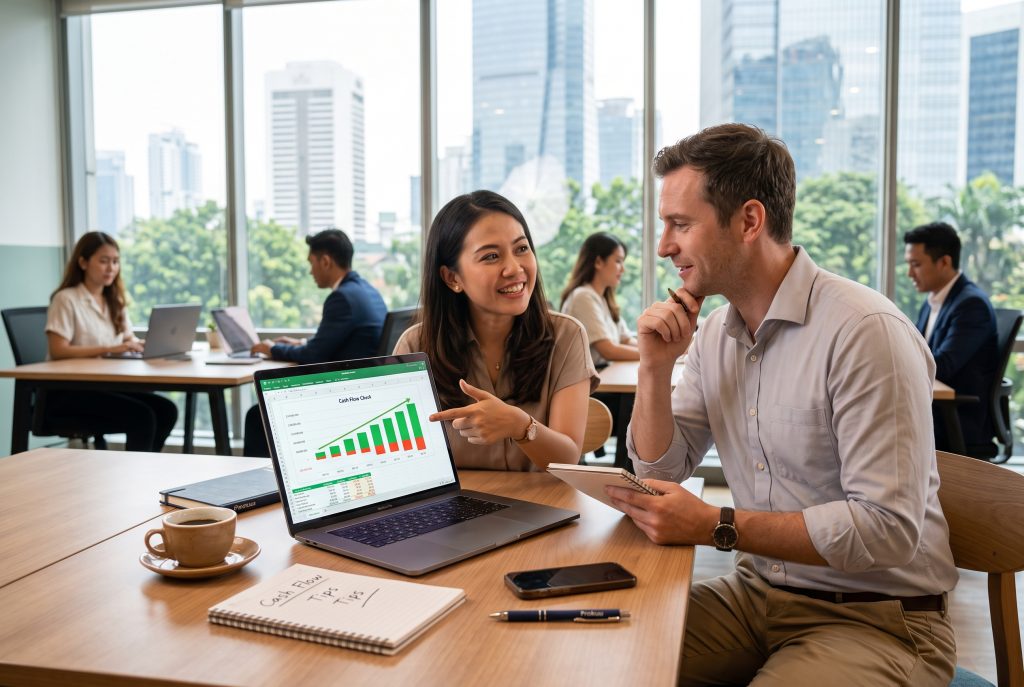
Do not drive a business just by looking at today’s bank balance. Make cash movement estimates for the next 3 to 6 months. Map out when funds are estimated to come in from customers and when specific routine expenditure dates must be paid. In this way, you can detect potential cash deficits long before a crisis occurs and take anticipated actions earlier.
2. Separate Operational and Emergency Reserve Accounts
Mixing daily operational funds, retained earnings, and emergency reserve funds in the same account is a fatal mistake. Implement a fund allocation system with discipline. As soon as revenue comes in, set aside a certain percentage to a special account as a business reserve fund (cash buffer) that is minimally able to cover 3 to 6 months of fixed operational costs.
3. Tighten Accounts Receivable Management
To speed up the turnover of incoming cash, implement stricter accounts receivable policies. You can offer a small discount for customers who pay earlier (early payment discount), enforce a down payment (DP) before work begins, as well as diligently send reminders before invoices fall due.
Right Steps When Cash Flow Starts Getting Strained
If your business starts experiencing symptoms of cash deficit—where expenditures are larger than cash receipts—immediately take measured efficiency steps:
- Renegotiate Vendor Payment Terms: Communicate transparently with main suppliers to extend payment time periods (payment terms) without damaging the partnership relationship.
- Audit and Cut Non-Essential Expenditures: Re-evaluate all software subscriptions, inefficient facility costs, or marketing expenditures that do not provide real returns on investment (ROI).
- Liquify Non-Productive Assets: Consider selling old inventory at a discount price or renting out rarely used equipment to get fresh funding injections quickly.
Maintaining Business Growth Sustainability
Meticulous cash flow management provides resilience and peace of mind for business owners. When cash turnover is regular and safe, you not only avoid the risk of default, but also have a strong financial foundation to capture new investment opportunities as well as execute long-term growth plans with confidence.
Business Cash Flow Management Guide: How to Avoid Running Out of Capital
Have you ever seen a business where sales seem to be booming, but the owner often gets a headache when having to pay daily operational bills? This phenomenon is very common in the business world. In accounting, there is a classic expression that is very relevant to this situation: “Profit is vanity, cash is sanity, but cash flow is king.”
Profit on paper (income statement) may look happy. However, the real cash capital in the bank account is what determines whether your business can survive tomorrow morning or not. Poor cash flow management is the primary cause why many companies—especially those growing rapidly—suddenly go bankrupt mid-way.
Why Can High-Revenue Businesses Run Out of Cash?
Many novice entrepreneurs think that increasing sales is the only cure to overcome financial problems. Unfortunately, growing without direction can actually become a deadly trap known as overtrading.
There are several fundamental reasons why business cash flow can suddenly dry up:
- Bottleneck in Accounts Receivable: You successfully sell products in large quantities, but buyers use a tempo payment system (30 to 90 days). Invoices pile up as assets, but you don’t have cash to buy new raw materials or pay the team’s salary.
- Accumulation of Dead Stock: Too much capital is tied up in the form of finished goods or inventory in the warehouse that has a very slow turnover. Your money stops moving.
- Timing Mismatch: The schedule of operational expense payment obligations (rent, vendor debt, taxes) falls due much faster than the schedule of cash receipts coming in from customers.
Basic Rules for Managing Healthy Cash Flow
Managing cash flow is not just about recording daily income and expenses in a general cash book. It is about controlling the rhythm and movement of fresh funds so they are always available in safe proportions.
1. Create Cash Flow Projections (Cash Flow Forecasting)
Do not drive a business just by looking at today’s bank balance. Make cash movement estimates for the next 3 to 6 months. Map out when funds are estimated to come in from customers and when specific routine expenditure dates must be paid. In this way, you can detect potential cash deficits long before a crisis occurs and take anticipated actions earlier.
2. Separate Operational and Emergency Reserve Accounts
Mixing daily operational funds, retained earnings, and emergency reserve funds in the same account is a fatal mistake. Implement a fund allocation system with discipline. As soon as revenue comes in, set aside a certain percentage to a special account as a business reserve fund (cash buffer) that is minimally able to cover 3 to 6 months of fixed operational costs.
3. Tighten Accounts Receivable Management
To speed up the turnover of incoming cash, implement stricter accounts receivable policies. You can offer a small discount for customers who pay earlier (early payment discount), enforce a down payment (DP) before work begins, as well as diligently send reminders before invoices fall due.
Right Steps When Cash Flow Starts Getting Strained
If your business starts experiencing symptoms of cash deficit—where expenditures are larger than cash receipts—immediately take measured efficiency steps:
- Renegotiate Vendor Payment Terms: Communicate transparently with main suppliers to extend payment time periods (payment terms) without damaging the partnership relationship.
- Audit and Cut Non-Essential Expenditures: Re-evaluate all software subscriptions, inefficient facility costs, or marketing expenditures that do not provide real returns on investment (ROI).
- Liquify Non-Productive Assets: Consider selling old inventory at a discount price or renting out rarely used equipment to get fresh funding injections quickly.
Maintaining Business Growth Sustainability
Meticulous cash flow management provides resilience and peace of mind for business owners. When cash turnover is regular and safe, you not only avoid the risk of default, but also have a strong financial foundation to capture new investment opportunities as well as execute long-term growth plans with confidence.